

PERA Survivor Benefit Options:
A Guide for Minnesota Public Employees
Choosing your PERA survivor benefit option is one of the most important retirement decisions you may make as a Minnesota public employee.
Your pension decision affects more than your monthly payment. It can also shape your spouse’s income, your family’s long-term security, your Social Security strategy, your investment withdrawals, your tax picture, and your estate plan.
At Mullins Financial, we help Minnesota public servants understand how these decisions fit together before retirement paperwork is submitted.
Why Your PERA Survivor Election Matters
When you retire from PERA, you typically choose between a single-life benefit and a survivor benefit option.
A single-life benefit generally provides the highest monthly payment during your lifetime. A survivor benefit option reduces your monthly pension payment during your lifetime, but it can continue income to the person you name as your survivor after your death.
PERA currently lists four survivor options: 25%, 50%, 75%, and 100%. Your monthly amount is reduced based on the option selected and the age of your named survivor. In general, the younger the survivor, the larger the reduction.
This is not simply a question of choosing the highest pension check. It is a question of balancing income today with protection for the person who may rely on that income later.
What Are the PERA Survivor Benefit Options?
With a PERA survivor option, you choose a percentage of your monthly benefit that would continue to your named survivor after your death.
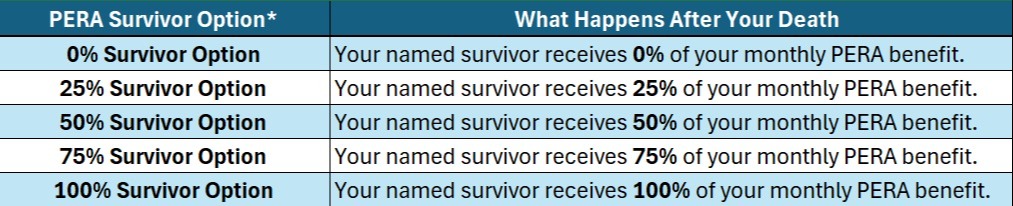
The higher the survivor percentage, the lower your monthly pension payment is during your lifetime.
For example, the 100% survivor option may provide the most income protection for your named survivor, but it also usually creates a larger reduction to your monthly pension payment. The 25% or 50% option may allow for a higher monthly benefit during your lifetime, but it may provide less protection for your survivor.
Planning note*:
If your named survivor dies before you, PERA’s bounce-back provision may increase your monthly benefit to the larger single-life amount, including applicable annual increases. However, you generally cannot name a replacement survivor. If any member contributions remain when you later pass away, those may be paid as a lump-sum death benefit to your named beneficiary. Always confirm your specific benefit options directly with PERA before submitting retirement paperwork.
PERA’s official materials describe the single-life option, the four survivor options, the bounce-back provision if the named survivor dies first, and the possibility of remaining contributions being paid as a lump sum to beneficiaries.
Questions to Ask Before Choosing a Survivor Option
Before selecting your PERA pension option, it helps to look at the whole financial picture.
Consider these questions:
- Would your spouse or survivor need your pension income to maintain their lifestyle?
- How much guaranteed income would continue from Social Security?
- Do you have life insurance that could replace some or all of the pension income?
- Do you have 457(b), 403(b), IRA, Roth IRA, or investment accounts that could provide survivor income?
- Is your spouse younger, older, healthier, or less financially independent?
- Would a larger monthly pension today create more flexibility during your retirement?
- Would a smaller pension with survivor protection provide more peace of mind?
- How would this decision affect your tax picture in retirement?
There is no one-size-fits-all answer. The right choice depends on your income needs, health, family situation, other assets, and how much risk you are comfortable leaving to your spouse or survivor.
Why This Decision Should Not Be Made in Isolation
A PERA survivor election is often treated like a pension form decision.
In reality, it is a retirement income decision.
Your survivor option should be reviewed alongside:
- Social Security timing
- Spousal and survivor Social Security benefits
- 457(b), 403(b), IRA, and Roth IRA withdrawal strategies
- Life insurance coverage
- Long-term care risk
- Estate planning documents
- Beneficiary designations
- Minnesota and federal income taxes
- Required minimum distributions later in retirement
For many Minnesota public employees, the pension is one of the largest retirement assets they have.
Choosing the survivor option without coordinating the rest of the plan can create unintended gaps.
A Common Mistake: Comparing Only the Monthly Pension Amount
One of the most common mistakes is choosing the option with the highest monthly payment without understanding what happens if the retiree dies first.
Another common mistake is choosing the highest survivor benefit without considering whether other assets, Social Security, or life insurance already provide enough protection.
The goal is not always to maximize the pension check. The goal is to create a retirement income plan that works for both spouses across different life scenarios.
Can You Change Your PERA Survivor Option Later?
This is one reason the decision deserves careful review.
PERA states that the benefit selection, named survivor if a survivor option is elected, and benefit effective date become final on the date PERA issues the first benefit payment.
Because rules can change and individual situations vary, you should confirm current details directly with PERA before submitting paperwork.
What If Your Named Survivor Dies Before You?
This is an important planning point because it often comes up when Minnesota public employees are comparing the single-life option to a survivor option.
PERA has a “bounce back” provision. If you choose a survivor option and your named survivor dies before you, your monthly benefit increases, or “bounces back,” to the larger single-life benefit amount. PERA explains that this is the amount you would have received had you not chosen to name a survivor, including annual increases that have accrued.
In plain language, choosing a survivor option does not necessarily mean you are permanently stuck with the reduced monthly amount if your spouse or named survivor passes away first.
A few details matter:
- You generally cannot name a second survivor after the first named survivor dies.
- The bounce-back provision applies when the survivor dies first.
- If any member contributions remain when you later pass away, those may be paid as a lump sum to your named beneficiaries.
- PERA needs to be notified of the survivor’s death before the benefit can be updated.
For planning purposes, this can reduce one common concern: “What if I choose the survivor option, take the lower monthly payment, and then my spouse dies before me?”
The answer is that PERA’s bounce-back provision may restore your benefit to the single-life amount. That does not make the survivor decision automatic, but it does make the tradeoff easier to evaluate with the full picture in mind.
You still want to compare the options alongside your spouse’s income needs, Social Security survivor benefits, life insurance, 457(b), 403(b), IRA and Roth IRA accounts, taxes, and estate plan before submitting your retirement paperwork.
Special Considerations for Non-Spouse Survivors
If your named survivor is not your spouse, age restrictions may apply when selecting certain survivor options, especially the 75% and 100% options. PERA’s retirement application materials state that non-spouse age restrictions apply to the 75% or 100% survivor option, but not to the 25% or 50% survivor option.
This is another reason to review your estimate, confirm the available options with PERA, and understand how the choice fits your full retirement plan.
How We Help Minnesota Public Employees Evaluate PERA Survivor Options
At Mullins Financial, we help Minnesota public servants move from scattered retirement decisions to one coordinated plan.
Using the CLARITY Retirement Method™, we review how your PERA pension fits with:
- Your retirement income goals
- Your spouse or survivor’s needs
- Social Security timing
- 457(b), 403(b), IRA, and Roth IRA accounts
- Tax-smart withdrawal strategies
- Insurance and risk management
- Estate and beneficiary planning
The goal is to help you understand the tradeoffs before making a decision that may affect your family for decades.
Before You Submit Your PERA Retirement Paperwork
Before you finalize your PERA election, take time to review the decision in the context of your full retirement plan.
A good survivor benefit decision should answer three questions:
- What income do we need while both spouses are living?
- What income would continue if one spouse dies first?
- What assets, insurance, and Social Security benefits help fill the gap?
If you are within a few years of retirement from Minnesota public service, this is a good time to review your pension options, Social Security strategy, tax plan, and retirement income plan together.
SCHEDULE A CLARITY RETIREMENT BLUEPRINT SESSION
If you are a Minnesota public employee, first responder, educator, healthcare professional, or government employee preparing for retirement, we can help you evaluate how your PERA survivor option fits into your bigger retirement picture.
Schedule a CLARITY Retirement Blueprint session to review your pension, Social Security, retirement accounts, taxes, and survivor planning before making your final election.
Important Disclosure
Mullins Financial is not affiliated with PERA. This page is for educational purposes only and is not intended as financial, tax, or legal advice. It should not be treated as a substitute for official PERA guidance. Pension rules, application procedures, tax laws, and benefit options can change. Always confirm your specific options directly with PERA before submitting retirement paperwork.